
Egypt signs a $1 billion World Bank financing agreement to advance economic reforms, attract private investment, strengthen social protection, improve public finances and accelerate its green economy transition.
Egypt has signed a $1 billion financing agreement with the World Bank to support its economic reform programme, strengthen resilience against external economic shocks and accelerate the transition towards a greener economy. The second phase of the World Bank’s Development Policy Financing (DPF) programme, titled “Building Resilience, Creating Opportunities and Enhancing Wealth for Egypt’s Prosperity and Stability.”
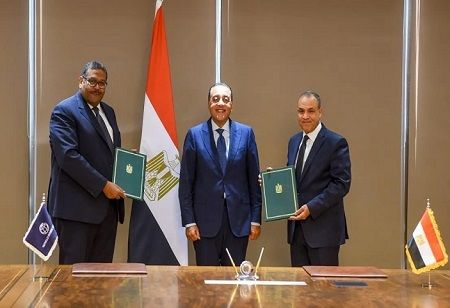
Prime Minister Mostafa Madbouly witnessed the signing ceremony at the Ministry of Foreign Affairs headquarters in Egypt’s New Administrative Capital. Foreign Minister Badr Abdelatty, who also serves as Egypt’s governor at the World Bank, signed the agreement with Alwaleed Alatabani, the World Bank’s Division Director for Egypt, Yemen and Djibouti. Planning and Economic Development Minister Ahmed Rostom and Deputy Finance Minister Yasser Sobhy also attended the event.
Also Read: Real-time Data Applications for Seamless Inventory and Delivery Management
The financing is designed to improve the competitiveness of the Egyptian economy, strengthen public finances and create a more favourable environment for private sector investment and job creation. Its reform agenda includes improving the governance of state-owned enterprises, removing regulatory barriers to private investment, promoting fair competition and strengthening domestic revenue mobilisation. The programme also aims to improve the efficiency of domestic debt markets and reduce government borrowing costs.
The second phase incorporates social and environmental reforms alongside economic measures. These include expanding the beneficiary base of the Takaful and Karama social protection programmes, improving greenhouse gas emissions monitoring systems and developing carbon credit markets. The programme also focuses on strengthening the financial sustainability of the electricity and water sectors to support the country's green transition.
The World Bank Group approved the $1 billion financing package on May 8, 2026. It comprises $800 million in World Bank financing, supported by a $200 million credit guarantee from the United Kingdom. The funding represents the second operation in a three-phase concessional development financing programme for Egypt.
Also Read: Enhancing Agricultural Productivity Through AI-Powered Digital Tools
The agreement aligns with the World Bank Group’s Country Partnership Framework for Egypt for 2023-2027 and supports the country’s broader economic reform priorities, including the State Ownership Policy, government privatisation programme, Egypt Vision 2030 and National Climate Change Strategy 2050.
Through the financing, Egypt aims to attract greater private investment, improve economic stability, protect vulnerable households and strengthen its capacity to address global economic and climate-related challenges.